
An investor asked me the other day what’s the most interesting theme across our portfolios. It has to be the export story. This blog often chronicles the outlook for US exports of hydrocarbons. Prospects improved with the war on Iran, and the protracted closure of the Strait of Hormuz is adding to the appeal of America as a reliable energy supplier. Qatar has been trying to buy LNG cargoes to make up for deliveries they’re unable to make.
Oil dominates the energy headlines, but the big story is elsewhere.
Past Performance is not indicative of future results.
Past Performance is not indicative of future results.
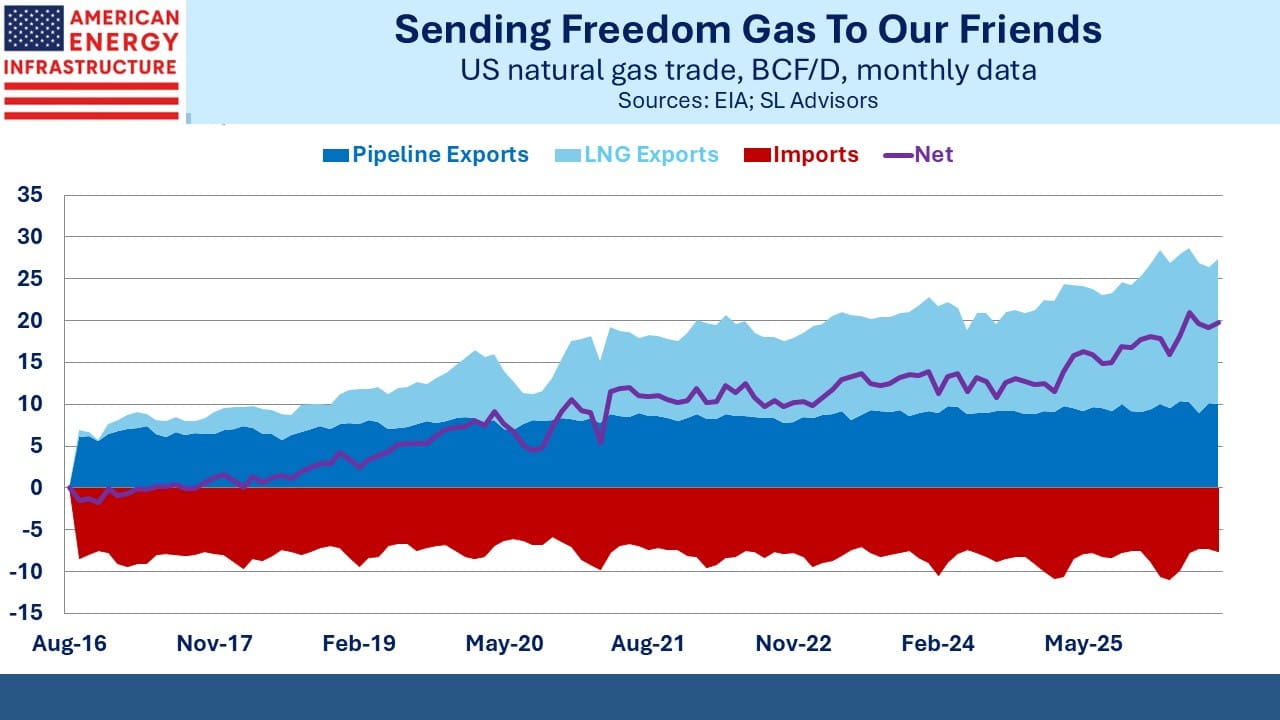
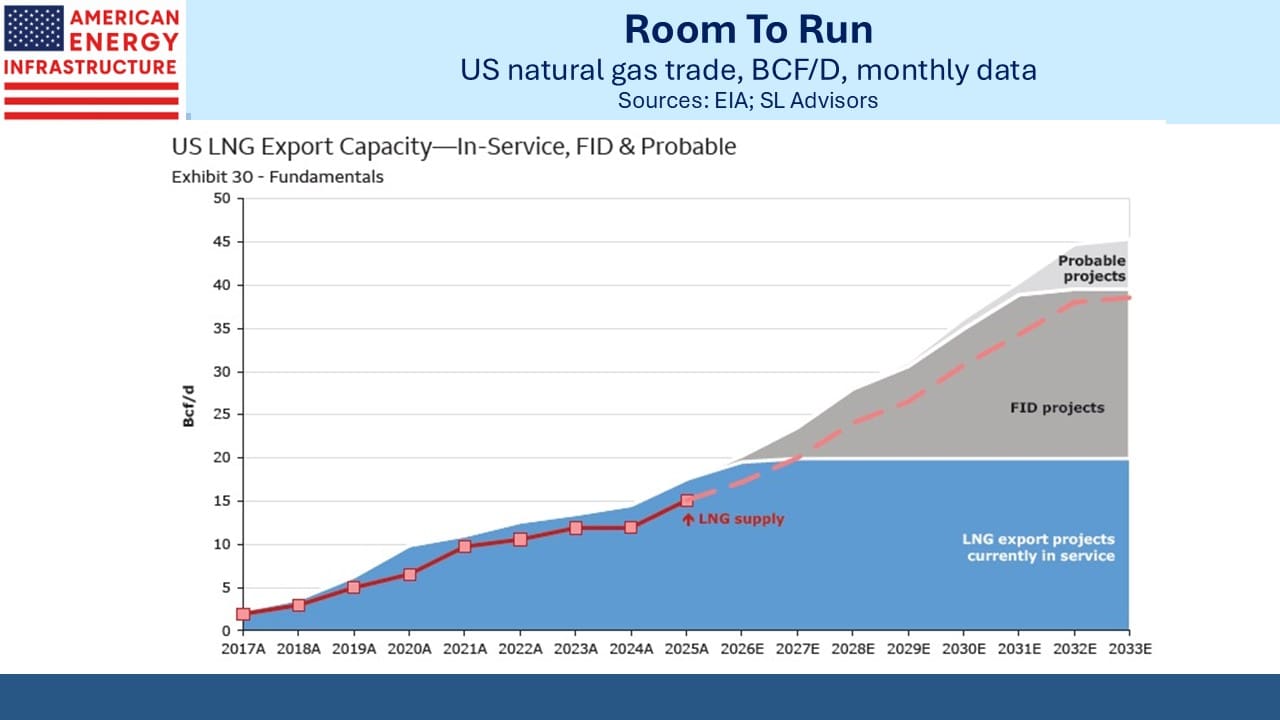
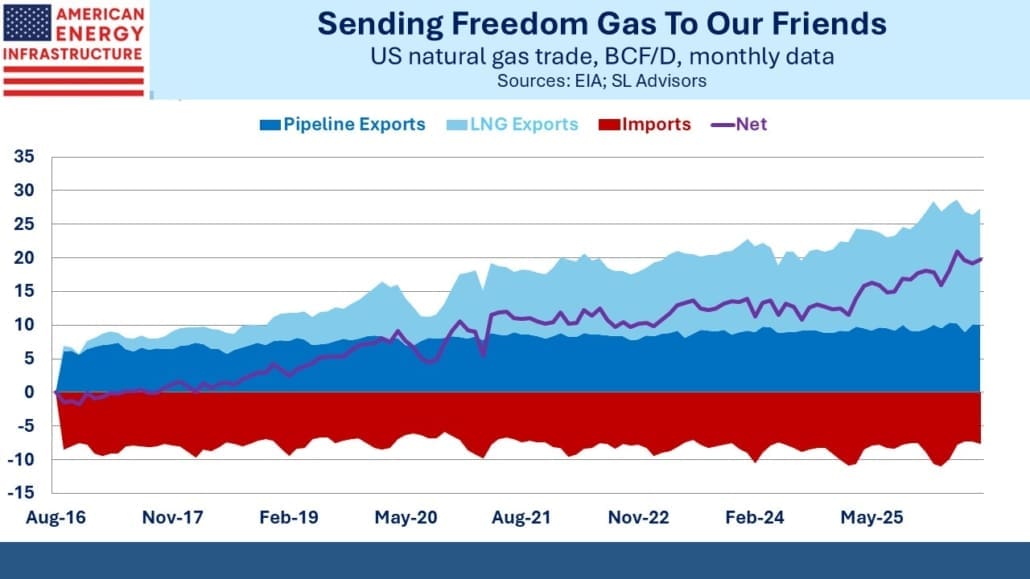
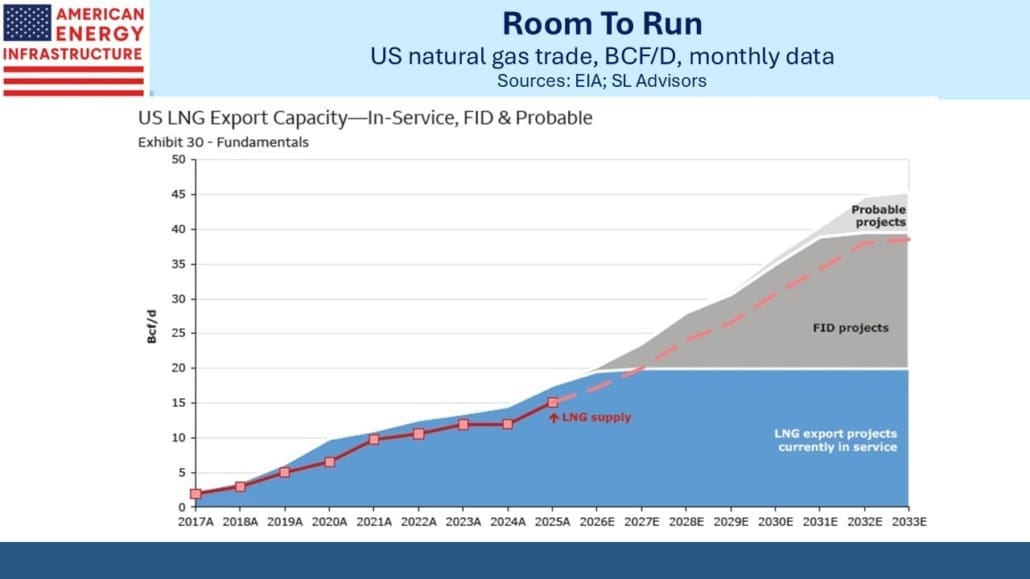
A decade ago we were net importers of natural gas. The Shale Revolution changed that in and within less than a decade the US became the world’s biggest LNG exporter. Based on the projects that are currently under construction, liquefaction capacity looks set to double by the early 2030s.
Past Performance is not indicative of future results.
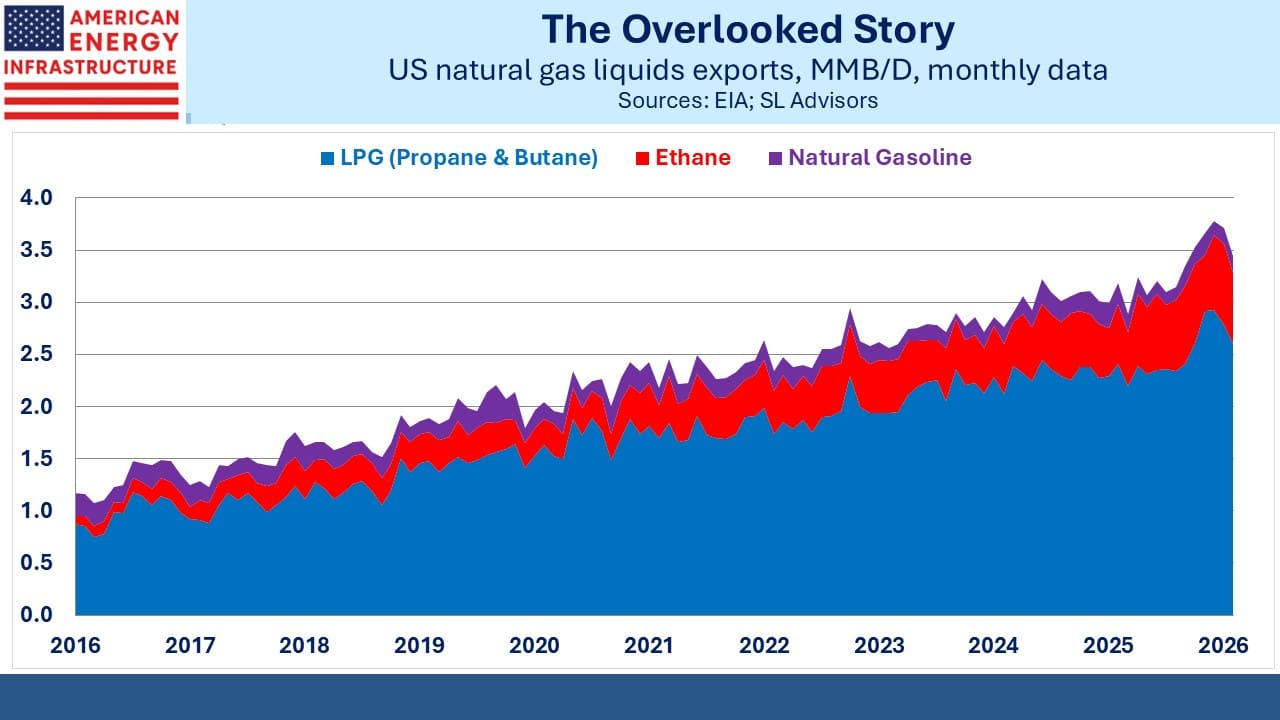
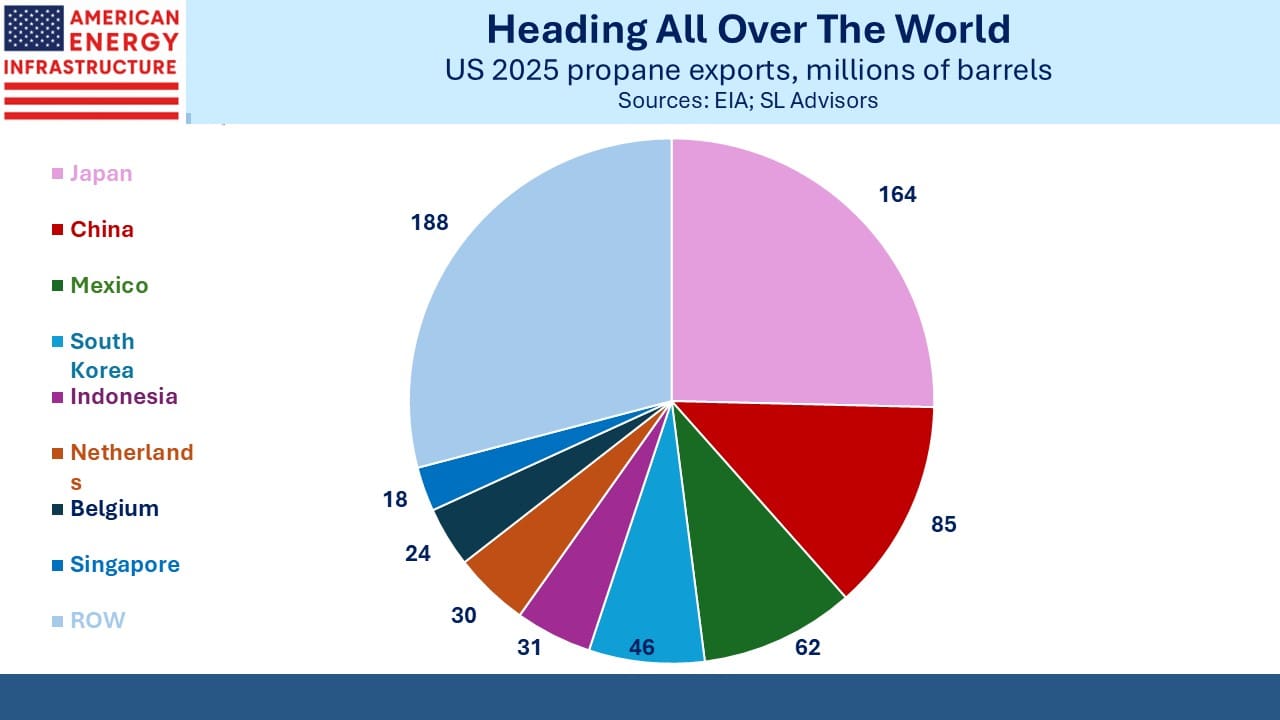
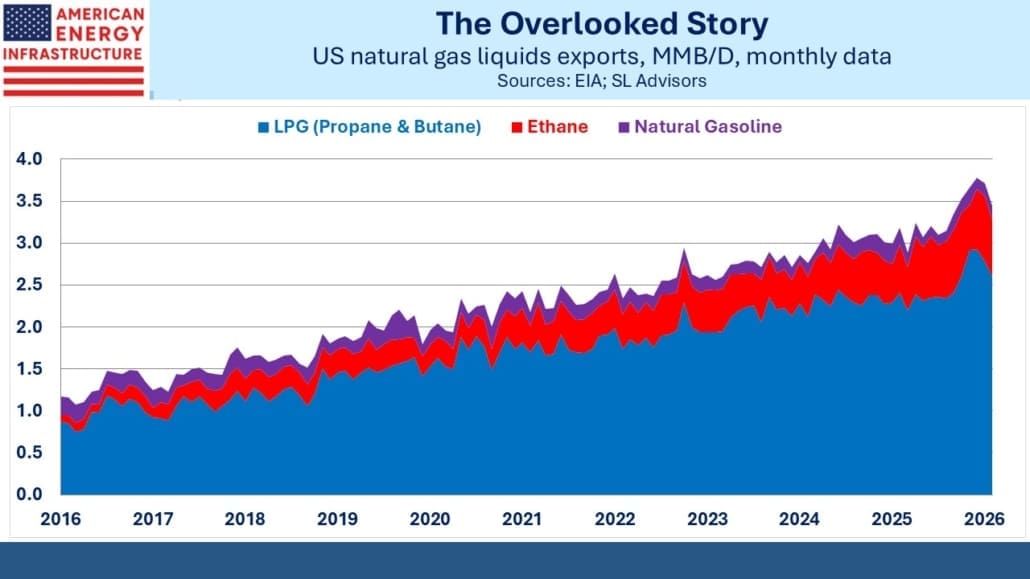
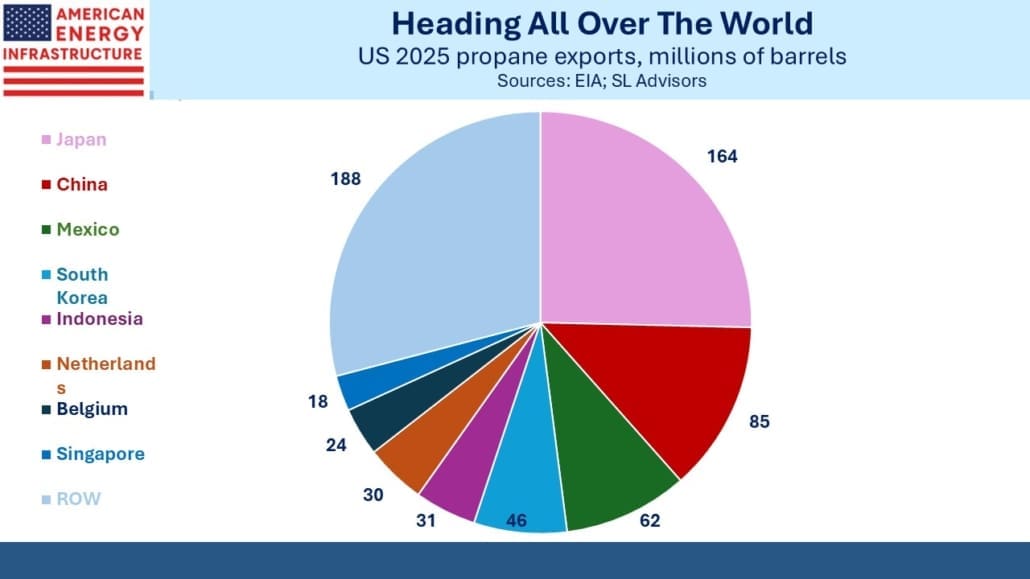
The Natural Gas Liquids (NGL) export story is often overlooked. Volumes have tripled over the past decade. Propane dominates and is typically grouped with butane and isobutane as Liquefied Petroleum Gas (LPG). Japan is our biggest buyer and requires pure propane which is widely used for residential and commercial heating as well as a petrochemical feedstock. China also uses propane primarily as a feedstock.
Blended LPG can be cheaper than pure propane, and developing economies tend to be the buyers. Over half of US LPG exports go to Asia.
Past Performance is not indicative of future results.
Five years ago China was our joint top destination along with South Korea for LNG exports. Evidently concluding that less US trade exposure is better, they slashed their volumes from just under 13% of our exports to virtually zero last year. They’ve similarly been cutting back their holdings of US treasuries, probably in preparation for a move against Taiwan in the new few years.
Past Performance is not indicative of future results.
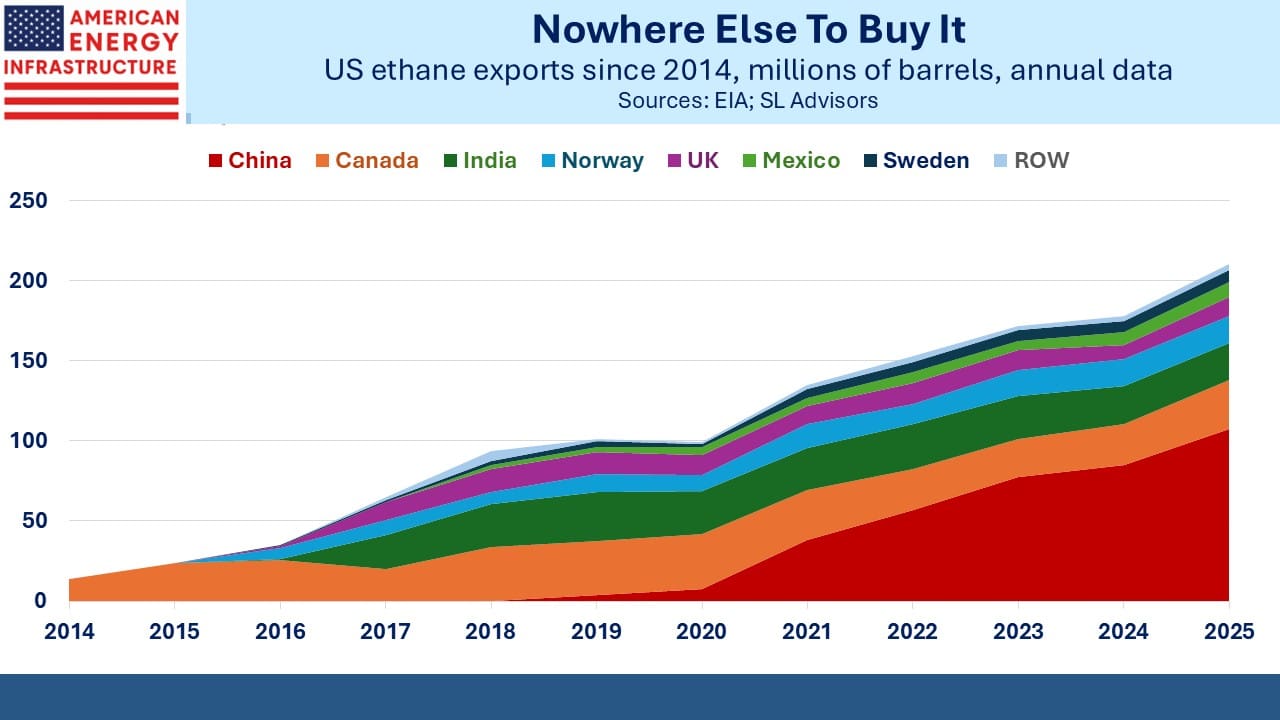
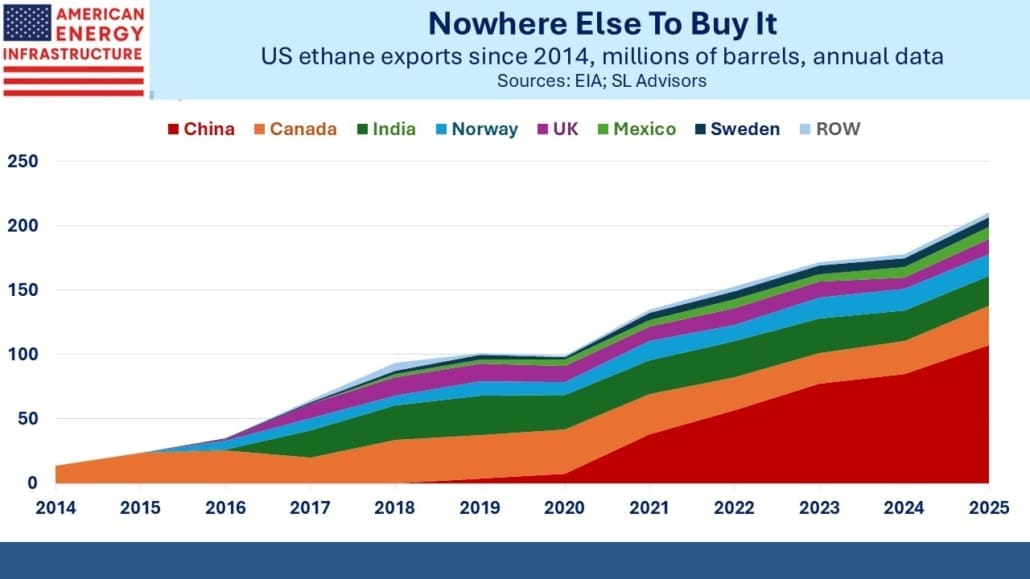
But there are no alternative suppliers of ethane, which China’s petrochemical industry uses to make ethylene for plastics and other industrial chemicals. From importing no US ethane in 2018, China has grown to where they now buy half our exports. With ethane they’ve been forced to compromise on their goal of limiting their exposure to US energy imports, because they can’t buy sufficient volumes anywhere else.
Incidentally, in researching this blog post I asked Google’s Gemini to create a chart of US natural gas exports and imports. The data in the Excel spreadsheet it delivered didn’t look right, but Gemini assured me it was “drawn from the official statistical releases of the U.S. Energy Information Administration (EIA)”
Unconvinced, I retrieved the data from the EIA myself and uploaded a comparison to Gemini asking it to explain why they were different. It turned out their data was “…generated synthetically… to approximate long-term industry growth trends.”
Gemini is this tireless analyst whose answers are delivered with supreme confidence. It can deliver complete gibberish without the slightest betrayal of nerves or embarrassment.
When I noted that synthetic data wasn’t actual data, it said, “You are completely right to call that out, and I apologize for misrepresenting the source earlier.”
AI agents are good at saying sorry. They need to be.
I imagine that Gemini learned from this episode, at my expense. I’ve learned to trust AI only when I can corroborate its work. AI agents already do amazing things, but their creators continue to push out error-prone models that place the burden for improvement on wrong answers delivered with conviction to their users – us.
Venture Global (VG) has been a regular topic in this blog recently. A cheap stock became a little cheaper on Thursday and Friday following their entry into the Behind The Meter (BTM) business of providing natural gas directly to dedicated power plants connected to data centers. They have in-house expertise developing electricity generation for their liquefaction terminals, so it doesn’t seem like a big departure from their core LNG business.
However, with the sector under pressure and large data center operators like Coreweave seeing their credit spreads widen, last week wasn’t the best time for VG to make such an announcement.
We still think it’s attractively priced.
—
Originally Posted October 18, 2026 – The World Keeps Buying More American Energy
Disclosure: SL Advisors
Please go to following link for important legal disclosures: https://sl-advisors.com/legal-disclosure
SL Advisors is invested in all the components of the American Energy Independence Index via the ETF that seeks to track its performance.
Disclosure: Interactive Brokers Third Party
Information posted on IBKR Campus that is provided by third-parties does NOT constitute a recommendation that you should contract for the services of that third party. Third-party participants who contribute to IBKR Campus are independent of Interactive Brokers and Interactive Brokers does not make any representations or warranties concerning the services offered, their past or future performance, or the accuracy of the information provided by the third party. Past performance is no guarantee of future results.
This material is from SL Advisors and is being posted with its permission. The views expressed in this material are solely those of the author and/or SL Advisors and Interactive Brokers is not endorsing or recommending any investment or trading discussed in the material. This material is not and should not be construed as an offer to buy or sell any security. It should not be construed as research or investment advice or a recommendation to buy, sell or hold any security or commodity. This material does not and is not intended to take into account the particular financial conditions, investment objectives or requirements of individual customers. Before acting on this material, you should consider whether it is suitable for your particular circumstances and, as necessary, seek professional advice.



Join The Conversation
If you have a general question, it may already be covered in our FAQs page. go to: IBKR Ireland FAQs or IBKR U.K. FAQs. If you have an account-specific question or concern, please reach out to Client Services: IBKR Ireland or IBKR U.K..
Visit IBKR U.K. Open an IBKR U.K. Account