Fed Governor Christopher Waller is sparking a market rally today after he hinted at a September pause. His positive comments on the softening trajectory of inflation arrived on the heels of yesterday’s remarks from NY Branch President John Williams, another permanent voting official, who echoed the same message of easing cost pressures. Moreover, Treasury Secretary Scott Bessent additionally boosted optimism on Wednesday when he declared that interest rates will fall once the Middle East conflict is resolved and oil cheapens. The trio of leaders delivering dovish perspectives is driving stocks higher for the second consecutive session while Treasuries are gaining notably with leadership from the monetary policy sensitive shorter tenors, which is creating a bull-steepening descent across the curve amidst a depreciating greenback. An increase in Challenger job cuts supported fixed-income assets too, although that tailwind was offset by subdued unemployment claims. Equities are jumping broadly as 10 of 11 sectors and all subsectors advance against the backdrop of the four major domestic benchmarks climbing meaningfully. Commodities and are also soaring, because sinking yields, a weaker dollar and ongoing geopolitical tensions are bolstering precious metals, copper, lumber, energy and bitcoin. Elsewhere, volatility protection instruments are getting tossed due to the risk-on attitude on Wall Street.
Unemployment Claims Signal Stability
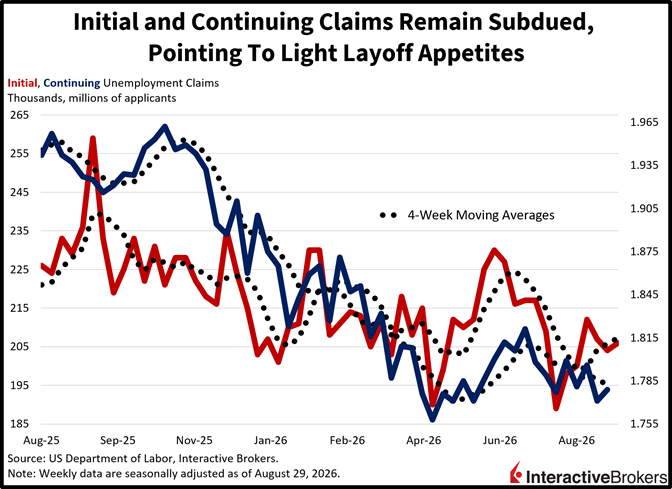
Labor conditions remained stable in the past two weeks according to this morning’s unemployment claims release. Initial and continuing filings rose slightly to 206k and 1.779 million in the seven-day periods ended on August 29th and 22nd, arriving ahead of the 204k and 1.771 million from the prior print. First-time applications were expected to come in at 205k. Four-week moving averages were little changed at 207.25k and 1.782 million compared to the 205.75k and 1.787 million from the preceding report.
Past performance is not indicative of future results.
But Expectations for Layoffs Jump
In a separate labor matter, the Challenger, Gray and Christmas report signaled an increase in August job cut plans although the overall publication was healthy. Layoff intentions amounting to 51.9k marked a 58% month-over-month (m/m) jump but a 38% year-over-year (y/y) reduction. Artificial intelligence adoption dropped to second on the list of reasons to trim payrolls, surrendering its leadership position for the first time since February, as restructurings took the top stop. Hiring objectives fell 23% m/m; however, they rose 37% y/y.
Expecting the Fifth Straight Month of Weaker Payrolls To Extend Treasury Rally
I’m expecting the fifth month in a row of weaker payrolls to extend today’s Treasury rally. Indeed, the second consecutive print of job losses is poised to raise slowdown risk and lead bond buyers onto the long end of the curve. Furthermore, Fed committee members will be evaluating the numbers to inform their perspective on which way they will vote on September 16. Dovish comments from Waller, Williams and Bessent have helped to significantly reduce the odds of a hike in 13 days, as the probability of an increase is now at a coin-flip. Inflation statistics next week will also be pivotal; however, ongoing decreases in employment should be enough for the central bank to start considering the labor side of its mandate when prescribing policy, rather than maintaining an unwavering commitment to quelling price pressures.
International Roundup
China’s Service Sector Growth Accelerates
The growth of activity in China’s service sector hit a faster pace last month with the RatingDog China General Services PMI climbing from 50.4 in July to 51.4. The gauge depicts the contraction-expansion threshold with a level of 50. The growth surprised to the upside with a consensus of economists anticipating a print of only 50.6. While the August print was the second lowest in 14 months, the country’s service sector has expanded every month since January 2023. New sales, market demand, financial improvements and innovation all contributed to the stronger activity growth with domestic orders being the main source of the increase in orders. International orders also rose, but at a more modest rate. The growth of backlog work also continued but at a slower pace due to companies increasing their business capacity as companies expanded their payrolls. Input costs, however, climbed for the eighteenth consecutive month with labor, materials, oil fuel and increased procurement causing expenses to climb. Companies responded by raising their output prices for the third consecutive month. Looking ahead, service companies maintained a positive outlook with growing activity expected to be driven by planned business expansions, market growth, more promotion and improved strategies.
Hong Kong Sinks Into Contraction but Gate Prices Climb
Economic activity in Hong Kong weakened in August with the S&P Global Hong Kong SAR PMI dropping from 51 to 49.5, or 0.5 percentage points below the contraction-expansion threshold of 50. Even with weak demand and other factors pulling the gauge below 50 for the first time since April, gate prices ascended at their steepest rate since the start of the second quarter of 2023. Survey respondents also reported weakening demand, declining output and feeling increasingly downbeat about the future. Input costs climbed at the fastest pace in three months. Firms said the inflation was driven by higher costs for raw materials and staff-related expenses. Businesses responded by jacking up their prices to preserve margins, which dampened demand and caused output to fall for the first time since April. Among foreign markets, exports to Mainland China rose but sank modestly elsewhere. With the decline in orders, businesses decreased their purchases of input items, but inventories still climbed. In another tailwind, supplier performance deteriorated with the Middle East war causing lead times to lengthen to the greatest extent in more than 18 months. The weaker demand and resulting excess capacity caused businesses to reduce headcounts for the fifth consecutive month. Companies accomplished this by not replacing individuals who had voluntary left, but some survey respondents said a lack of available workers contributed to not filling vacant positions.
Canada’s Merchandise Trade Deficit Falls
Canada’s five consecutive months of export growth ended in July with the value of products shipped abroad declining 2.3%. In the same month, imports were up 0.6%, causing the country’s trade balance to fall from C$4.2 billion in June to C$769 million, according to Statistics Canada. Economists anticipated that the surplus would fall to only C$3.2 billion. July trading produced the first decline in exports in six months. Among the country’s 11 product sections, 7 experienced declines in shipments. Metal and non-metallic mineral products and exports of energy products posted the largest declines. Within the metals statistics exports of unwrought gold, silver, and platinum group metals, and their alloys sank 13.1%. Gold purchases weakened and there were fewer shipments to the US. In the energy category, crude oil shipments and 5.6%. On a positive note, the value of aircraft and other transportation equipment sent beyond Canada’s borders jumped 34.9%. Farm, fishing and intermediate food products also experienced increased demand from foreign markets. The higher levels of imports were driven by motor vehicles and parts shipped into the country ascending by 11.4%. Domestic purchases of metal and non-metallic mineral products from foreign providers also picked up in July.
New to Interactive Brokers?
Open AccountDisclosure: Interactive Brokers Affiliate
Information posted on IBKR Campus that is provided by third-parties does NOT constitute a recommendation that you should contract for the services of that third party. Third-party participants who contribute to IBKR Campus are independent of Interactive Brokers and Interactive Brokers does not make any representations or warranties concerning the services offered, their past or future performance, or the accuracy of the information provided by the third party. Past performance is no guarantee of future results.
This material is from IBKR Macroeconomics, an affiliate of Interactive Brokers LLC, and is being posted with its permission. The views expressed in this material are solely those of the author and/or IBKR Macroeconomics and Interactive Brokers is not endorsing or recommending any investment or trading discussed in the material. This material is not and should not be construed as an offer to buy or sell any security. It should not be construed as research or investment advice or a recommendation to buy, sell or hold any security or commodity. This material does not and is not intended to take into account the particular financial conditions, investment objectives or requirements of individual customers. Before acting on this material, you should consider whether it is suitable for your particular circumstances and, as necessary, seek professional advice.
Disclosure: Precious Metals
Precious metals may not be available in all locations, please check your local IBKR website for availability.


Join The Conversation
If you have a general question, it may already be covered in our FAQs page. go to: IBKR Ireland FAQs or IBKR U.K. FAQs. If you have an account-specific question or concern, please reach out to Client Services: IBKR Ireland or IBKR U.K..
Visit IBKR U.K. Open an IBKR U.K. Account